Automated Decision Infrastructure

Precision Intelligence for Automated Portfolio Entry

Keenmoor Partners combines predictive market modeling with algorithmic dollar-cost averaging to calibrate entry timing and mitigate exposure during high-volatility cycles. The system runs continuously, requiring no manual oversight once configured.
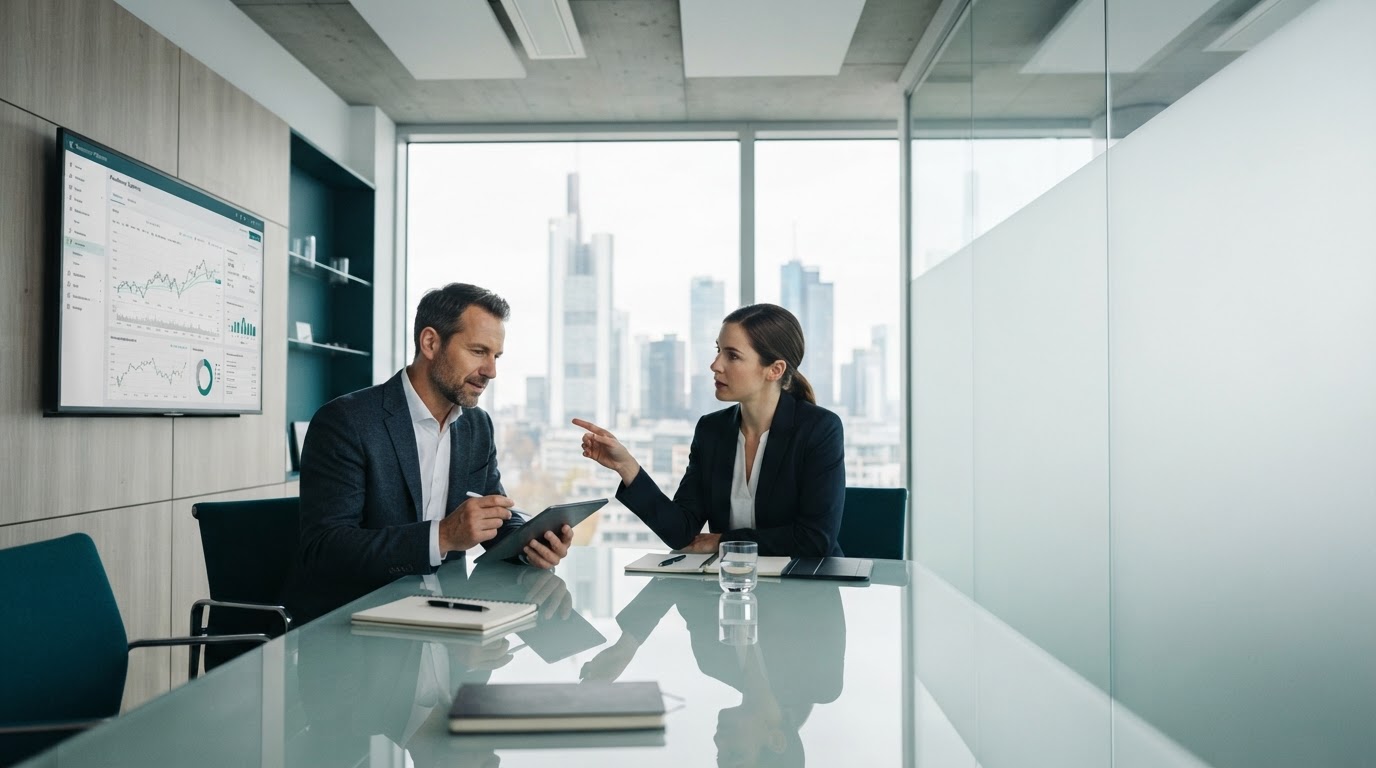
Keenmoor Partners data analysis dashboard showing automated investment signal processing
Illustrative Model Output — Entry Confidence by Interval
Volatility and Data Volume Outpace Manual Analysis

Side-hustle investors typically allocate limited hours to position review, yet markets generate continuous price, volume, and sentiment data. The result is what Keenmoor Partners categorizes as "Market Noise": a volume of signals too large for consistent human interpretation within constrained time windows.

A second constraint compounds the first. Entry and exit decisions made under time pressure are frequently shaped by "Emotional Bias" — the tendency to react to short-term price movement rather than underlying statistical trend. Keenmoor Partners functions as a rational filter positioned between raw market data and the investor's capital allocation, applying consistent, quantifiable rules rather than discretionary judgment.

  • Signal VolumePrice, volume, and derivative data streams update faster than manual review cycles allow.
  • Decision FatigueRepeated manual entry decisions degrade in consistency over extended holding periods.
  • Bias ExposureDiscretionary timing is susceptible to recency effects and loss aversion.
  • Oversight CostContinuous manual monitoring is impractical alongside a primary occupation.

Systematic Execution Without Manual Input

Each component operates on fixed, auditable logic. None rely on discretionary override during live execution.

01 / Predictive Modeling

Latency-Optimized Analysis

Market data is processed through statistical models trained to identify short-term price dislocations. Analysis latency is kept low enough that entry windows remain valid at the point of execution, rather than reflecting stale conditions.

02 / Automated DCA

Algorithmic Dollar-Cost Averaging

Capital is deployed across scheduled intervals, with allocation size adjusted by the model's confidence score for the current window rather than a fixed, calendar-based amount alone.

03 / Risk Adjustment

Predictive Risk Weighting

Position sizing is scaled against a rolling volatility estimate, reducing exposure automatically when short-term variance increases beyond defined thresholds.

A Transparent Three-Step Pipeline

The process below describes what occurs between data ingestion and capital deployment. No step is manually triggered once the system is active.

1

Data Aggregation

Price history, order-book depth, and volatility indices are collected from connected market data sources and normalized into a consistent format for model input.

2

Neural Analysis

Aggregated data is passed through the predictive model, which produces an entry-confidence score and a corresponding risk weighting for the current interval.

3

Automated Strategic Placement

Based on the output of step two, the system calculates allocation size and places the corresponding order within the user's predefined account parameters.

Comparing Manual Timing to Model-Driven Entry

Entry Method Comparison

Manual entry decisions are typically made at irregular intervals, often triggered by visible price movement after it has already occurred. Model-driven entry instead evaluates volatility and trend signals continuously, independent of whether the investor is actively watching the market.

FactorOutcome
Manual, Emotion-Based EntryIrregular, reactive
AI-Optimized TimingContinuous, rule-based
Decision FrequencyFixed by schedule, not mood
Oversight RequirementMinimal after setup
Cost-Basis Variance Scheduled, confidence-weighted purchases tend to reduce the spread of entry prices across an accumulation cycle compared with single lump-sum timing attempts.
Execution Consistency Automated placement removes the gap between decision and action, since orders are executed at the moment the model's conditions are met.

Cost-Basis Outcomes Over Multi-Cycle Accumulation

Because allocation size responds to the model's confidence score rather than a fixed schedule alone, average cost basis over a full accumulation cycle is a function of signal quality, not of when the investor happened to check the market. This does not eliminate market risk; it changes how allocation decisions are made within that risk.

Built for Oversight, Not Dependency

Keenmoor Partners was designed around a single constraint: side-hustle investors have limited time for active position management. The platform is built so that configuration, monitoring, and parameter review can be completed in short, periodic sessions, while execution logic runs independently in the background.

Every automated action is logged and reviewable, so the reasoning behind a given entry or allocation adjustment can be traced after the fact rather than taken on faith.

Read More About Keenmoor Partners
Keenmoor Partners team workspace used for model calibration and platform operations

Security, Control, and Integration

The answers below address the technical questions most frequently raised by investors evaluating automated execution tools in the DACH region.

How is account and market data protected?

Data transmitted between connected accounts and the platform is encrypted in transit and at rest, and processing is carried out in accordance with EU data protection requirements. Keenmoor Partners does not sell or share account data with third parties outside of the infrastructure required to execute the service.

Can automated execution be paused or restricted?

Yes. Allocation limits, maximum position size, and permitted asset classes are set by the user before automation begins. Execution can be paused at any time; the model will hold its position without placing new orders until resumed.

How does the platform connect to brokerage or exchange accounts?

Connections are established through read/write-scoped API keys issued by the supported broker or exchange, limited to order placement and balance reporting. Keenmoor Partners does not request withdrawal permissions as part of standard integration.

What happens if the predictive model's confidence is low?

Below a defined confidence threshold, the risk-weighting component reduces allocation size automatically, and in sustained low-confidence conditions, scheduled purchases are deferred rather than executed at full size.

Initialize Your Data Stream

Connecting an account and setting allocation parameters is the first step toward moving entry-timing decisions from manual review to continuous, model-driven execution.

Initialize Your Data Stream